Main Menu

CIBC Private Wealth

August 2026 Investment Bulletin

August 04, 2026• Markets & Economy, Wealth planning
Share

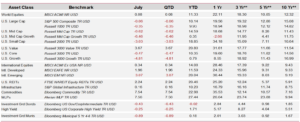
Global asset class total returns through 7.31.26*

*Source: FactSet. **Annualized

July key drivers:

  • FOMC and earnings: Fed policy and earnings reports were the primary drivers of market activity in July and will likely remain key contributors over the next month as well. For the month, most major US equity indices were flat, with the exception of mid- and small-cap indices, which were affected by higher rates. Middle East tensions remain on investors’ minds, but the real story is inflation, rates and corporate earnings.
  • Fed disappointment: It’s been quite some time since a Fed decision moved markets, but that changed in July. With expectations elevated for a rate hike, the Federal Open Market Committee (FOMC) did not raise its policy rate, which raised concerns among investors about the fight against inflation. As a result, the S&P 500 lost more than 1.5% between July 22 and July 23, while long-bond yields surged higher. Higher oil prices are making the inflation fight more difficult, putting pressure on Fed Chair Warsh.
  • Earnings exceeding expectations: Second quarter earnings continue to come in with solid results. However, it has become clear that investors are rewarding companies that meet or exceed expectations while punishing those that miss guidance. With more than 60% of companies in the S&P 500 having reported through the end of July, 86% have delivered better-than-expected earnings results. The current Q2 year-over-year growth rate is above 40%, which, if sustained, would be the highest since Q1 2021.1

What to watch in August:

  • Rising prices: With inflation being one of the top concerns for investors, the next CPI report, due on August 12, will be key. The data reported in July for June suggested some easing in price pressures, which was well received. However, the lack of Fed guidance and recent volatility in oil prices mean investors will be very focused on the data. Current expectations suggest a 0.2% increase for the month, but a slight year-over-year decrease in Core CPI.
  • Pivot in Middle East: With the situation in the Middle East worsening in July, investors are looking past the rhetoric but not past the impact of oil prices on the economy. Pressure is building for another attempt at a diplomatic solution to the war, not only from members of Congress but also from allies across the Gulf states. The closer we get to the midterm elections in November, the more likely it is that a diplomatic solution could be achieved.
  • Fed Chair message in late August: Although there is no Fed meeting in August, the late July decision and post-meeting comments continue to resonate across markets. Kevin Warsh is putting his imprint on the committee process, taking a somewhat different approach from what markets are used to. He has been consistent in saying that he wants to get inflation under control, but he has been vague in terms of how he plans to accomplish it. Chair Warsh could use his keynote address at Jackson Hole in late August to signal his strategy on inflation.

1 FactSet

Related solution

Investment management

Turning our investment legacy into
long-term growth for your portfolio.

Contributor

William Norris

William Norris

Managing Director•Head of Central Region

Related insights and perspectives

Markets & Economy

Financial markets outlook: Third quarter 2026

Earnings have remained the main driver of equity returns, with AI investment and broader earnings strength supporting a more sustainable market rally. Chief Investment Officer Gary Pzegeo, CFA, and Senior Equity Portfolio Manager, Bryan Reilly, discuss why markets have stayed resilient despite limited help from interest rates, and what investors should watch as AI demand and energy volatility shape the second half of 2026.

Let’s connect

It’s your wealth.
Together, we’ll make it your legacy.

Connect with an advisor