Main Menu

CIBC Private Wealth

September 2026 Investment Bulletin

September 03, 2026• Markets & Economy, Wealth planning
Share

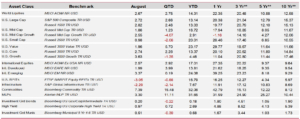
Global asset class total returns through 8.31.26*

Global asset class total returns through 8.31.26

*Source: FactSet. **Annualized

August key drivers:

  • Yield concerns increasing: Although higher bond yields created some headwinds for equities in August, strong earnings results drove markets higher. The S&P 500 gained over 2% in August, while large-cap growth companies, as measured by the Russell 3000 Index, gained over 3%. Rate-sensitive sectors such as REITs posted negative results, while commodities moved higher, driven by rising oil prices.
  • Cooling Economic Data: Softer consumer price data (CPI) and manufacturing price data left investors wondering whether the September Federal Open Market Committee (FOMC) meeting would result in a rate hike. The recent trend in US economic data suggests some cooling in the economy, while growth remains positive. Following the second revision, Q2 GDP growth came in at 1.5%, slightly weaker than expected.
  • Earnings, earnings, earnings: Over the past few months, we’ve highlighted the impressive earnings growth posted by many companies in the S&P 500, and that trend continued. With over 85% of companies reporting, Q2 earnings growth came in at 52%, the highest growth rate since Q2 2021. Even excluding a few of the larger tech companies in the index, the growth rate was still an impressive 34%. The surge in earnings has helped bring the forward P/E ratio below the S&P 500’s five-year average.1

What to watch in September:

  • Yield curve/rates: The bond market is currently where investors are most focused, as they monitor where rates may go in the coming months. Longer-dated yields (10- to 30-year bonds) have been moving higher, as concerns over inflation and excessive debt issuance weigh on markets. Expectations for a rate hike from the Fed at its next meeting have risen from 35% a month ago to over 65% as of September 1.
  • Economic data and Fed meeting: With growing concerns over elevated inflation and higher yields across the bond market, economic data will be key in September. Investors will be paying close attention to the release of data covering consumer prices, producer prices, retail sales, and the labor market. The next rate decision from the Fed will come on September 16, while the inflation data reports will be released on September 10 and 11.
  • Oil prices: Oil prices have remained elevated since the start of the conflict in the Middle East and continue to have an impact on markets. There is little evidence to suggest that oil flows have improved, and the recent announcement by the US government regarding the oil deal with Venezuela is not likely to lower gas prices for consumers anytime soon. Any sustained move higher in oil prices, particularly if Brent crude approaches $100 a barrel, could put more pressure on risk assets.


1 FactSet

Related solution

Investment management

Turning our investment legacy into
long-term growth for your portfolio.

Contributor

William Norris

William Norris

Managing Director•Head of Central Region

Related insights and perspectives

Markets & Economy

Economic and Financial Markets Outlook: Fourth Quarter 2026

Slow, steady growth remains the outlook—but not without risks. Chief Investment Officer Gary Pzegeo, CFA, and Head of Fixed Income Tim Musial, CFA, break down the effects of energy-driven inflation, the Fed’s next moves, and why higher corporate bond yields could shape business investment and earnings expectations heading into 2027.

Let’s connect

It’s your wealth.
Together, we’ll make it your legacy.

Connect with an advisor