

Related solution
Investment management
Turning our investment legacy into
long-term growth for your portfolio.
Consumer and commercial banking products and services are offered through CIBC Bank USA. Member FDIC and Equal Housing Lender. All loans are subject to credit approval. Trust services and investment products are offered by CIBC Private Wealth Management. CIBC Private Wealth Management includes CIBC National Trust Company, CIBC Delaware Trust Company and CIBC Private Wealth Advisors, Inc. (a registered investment adviser) all of which are wholly owned subsidiaries of CIBC Private Wealth Group, LLC — and the private banking division of CIBC Bank USA. Trust services and investment products are not FDIC insured, not deposits or obligations of, or guaranteed by, CIBC Bank USA or CIBC National Trust Company, and are subject to investment risk, including loss of principal.
Commercial real estate products and services offered by CIBC Bank USA and CIBC Inc.
CIBC Capital Markets is a trademark brand name under which CIBC and some of its subsidiaries, including CIBC World Markets Inc., CIBC World Markets Corp. and CIBC Bank USA, provide different products and services. Capital Markets products are not FDIC insured; not deposits or obligations of, or guaranteed by, CIBC Bank USA; and are subject to investment risk, including loss of principal.
This website is not intended for use by residents of the European Union (EU).


The CIBC Logo is a registered trademark of CIBC, used under license.
©2026 CIBC Bank USA.
As earnings season begins, there are great expectations
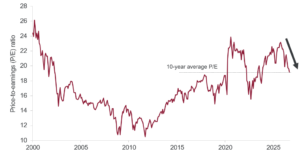
Earnings boom makes valuations look more reasonable
S&P 500 price-to-earnings ratio, 12-month forward EPS estimates
Source: FactSet, as of September 30, 2026.
Third-quarter corporate earnings reports will be arriving fast and furious throughout October. Consensus estimates call for total S&P 500 earnings to rise 29.5% from a year earlier, marking a third consecutive quarter of gains above 25%. While energy and technology companies are expected to lead the way, all 11 sectors are projected to post profit growth.
This earnings strength is even more notable in the context of the economic cycle. Growth rates like these are typically seen as the economy emerges from a recession and profits rebound from depressed levels. Yet the economy is now several years into an expansion.
One important byproduct of rapidly rising profits is that they make market valuations more reasonable. As the chart shows, the most widely used stock valuation measure, the price-to-earnings (P/E) ratio, has declined over the past year even as the S&P 500 reached all-time highs last week. That is because earnings have grown faster than stock prices. The P/E ratio now stands right at its 10-year average.
What we’re watching this week
Wednesday: The Consumer Price Index for September will be released. Economists expect a slight acceleration in the annual inflation rate.
Thursday: September retail sales will be reported, with estimates pointing to a small increase from the prior month.
Throughout the week: America’s largest financial institutions will report third-quarter earnings.


